Canaan’s 5X Comeback? Wall Street Sees Explosive Upside for Bitcoin Mining Rig Maker
Singapore-based Canaan Inc. (NASDAQ: CAN)—once viewed as a struggling crypto hardware firm—is now being spotlighted by Wall Street as a potential five-bagger opportunity. Despite a staggering 72% drop in its stock price year-to-date, a new bullish call from Benchmark analyst Mark Palmer suggests Canaan could rebound sharply, driven by strategic expansion in both Bitcoin ASIC manufacturing and proprietary mining operations.
Palmer, in his initiation report on Tuesday, gave Canaan a “Buy” rating with a price target of $3, implying a near 5X return from its current trading level of $0.62. For crypto-aligned CEOs, fund managers, and venture investors, this coverage signals an inflection point—not just for Canaan, but for the broader narrative around Bitcoin infrastructure equities.
What’s Driving the Bullish Bet?
Dual Strategy: Chips + Self-Mining
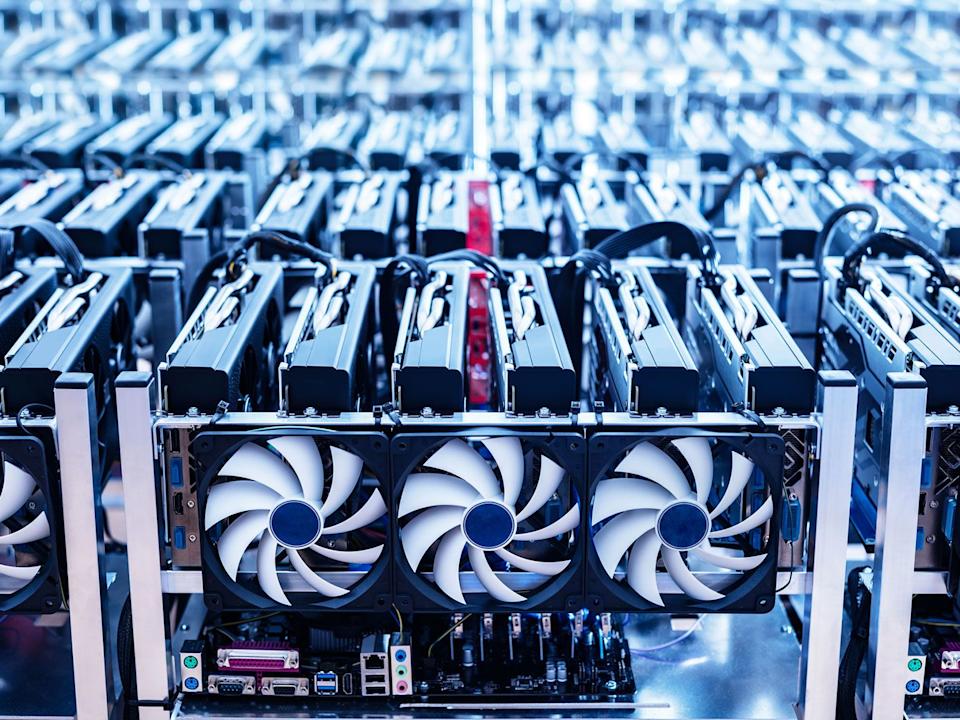
According to Palmer, Canaan’s long-term value hinges on its vertically integrated strategy. Unlike many crypto companies that either manufacture mining hardware or run mining farms, Canaan does both:
-
ASIC chip and rig development: These are sold to miners globally, providing high-margin, consistent revenue.
-
Self-mining operations: Canaan mines Bitcoin using its own machines, giving it direct exposure to BTC’s upside.
This hybrid model mirrors traditional semiconductor strategies—combining B2B hardware sales with vertically-owned use cases—and is key to Palmer’s bullish thesis.
“CAN’s vertically integrated approach differentiates it within the bitcoin mining space while positioning it to capitalize on both chip/rig sales and proprietary mining revenues,” Palmer wrote.
Expanding Mining Operations in the U.S. and Beyond
Building Global Hashrate Capacity
Canaan is also making a strategic geographic shift by scaling its self-mining presence in North America, a move that aligns with shifting global hashpower trends post-China ban. According to Palmer, Canaan plans to:
-
Increase total self-mining hash rate to 10 EH/s in North America
-
Expand to 15 EH/s globally by mid-2025
These targets represent a massive step-up from its current capacity, which contributed just 16.3% of total 2024 revenue. But that’s poised to change as Canaan leverages cheap energy deals and favorable regulation in U.S. mining hotspots like Texas and Wyoming.
This also gives the company better control over revenue cycles, buffering it from the periodic booms and busts of hardware demand.
Home Mining Push: A Strategic Diversification
Tapping Retail Demand for Sovereign Mining
Another angle investors shouldn’t ignore is Canaan’s entry into the home mining market. While not the primary revenue driver, it serves two key purposes:
-
Diversifies income streams
-
Builds brand equity with the retail crypto community
As Bitcoin adoption grows—and narratives around “owning your hashpower” gain traction—Canaan’s consumer-friendly rigs could become the ASIC equivalent of Nvidia’s gaming GPUs.
It’s a long-term play, but one that positions Canaan favorably in a segment underserved by enterprise-focused mining equipment giants.
Bitcoin Treasury Strategy Bolsters Financial Position
$133M in BTC Holdings Provide Downside Cushion
Beyond hardware and operations, Canaan’s treasury management is also drawing investor interest. As of the latest update, the company holds 1,408 Bitcoin, worth approximately $133 million—representing nearly 70% of its market capitalization.
“That should be supportive of the company’s valuation,” Palmer noted, emphasizing the embedded floor the Bitcoin holdings provide.
This reserve gives Canaan flexibility in downturns, potential for crypto-native capital appreciation, and a hedge against macro inflationary cycles.
It also puts them in the company of MicroStrategy, Marathon Digital, and Riot Platforms, which all employ similar BTC balance sheet strategies.
Why the Market Hasn’t Reacted Yet—And Why That Might Change
Oversold or Overlooked?
Despite the glowing analyst coverage, Canaan stock remains heavily discounted. Year-to-date, it’s down over 70%, a performance driven by:
-
Weak 2024 earnings due to low Bitcoin prices and ASIC demand slump
-
Concerns over Asian regulatory pressures
-
General risk-off sentiment in small-cap tech and crypto equities
However, Palmer’s call suggests that most of the bad news is priced in. If Bitcoin continues to hold above $60,000 and mining profitability improves post-halving, Canaan could stage a dramatic reversal, especially if its self-mining buildout hits targets.
What This Means for Leaders in the Crypto Space
For crypto executives, hedge fund CIOs, and venture investors, the Canaan story offers broader strategic takeaways:
-
Vertical integration is the future of Bitcoin infrastructure—owning both hardware and hashrate creates value capture across the mining stack.
-
Geographic agility matters—shifting capacity to U.S. markets can derisk regulatory exposure while tapping abundant clean energy sources.
-
BTC on balance sheet isn’t just a hedge—it’s a valuation support mechanism during equity drawdowns.
-
Consumer ASICs are a white space—early movers in home mining could build massive long-tail retail presence.
If you’re betting on Bitcoin as a sovereign computing layer, firms like Canaan are building the physical foundation. And if Palmer’s analysis proves correct, the upside could be a 5X return from today’s levels—a rare opportunity in a maturing, post-hype crypto landscape.
Disclaimer: The above press release has been provided by a third party. We do not verify or endorse the content and will not be responsible for any inaccuracies, claims, or damages arising from the same.